No new bills, no new coins, no crypto, and no central bank digital currency…
Yet I believe President Trump could be about to trigger the biggest change to America’s money in more than 50 years.
Not since the Nixon administration struck its secret deal in the desert to create the petrodollar has America seen a monetary shift as radical as the one I believe Trump is plotting right now.
And it doesn’t matter who controls Congress, this plan was set in motion behind closed doors in Washington.. and it’s being carried out through a series of emergency declarations, international pacts and executive orders, including Executive Order 14241.
Once you understand Trump’s dollar reset, the seemingly chaotic events of the past few years suddenly click into place:
The obsession with Greenland and annexing Canada, the seizure of Venezuela’s oil, the war in Iran, and the government’s billion-dollar stakes in obscure mining companies.
In my view, they’re all part of a larger plan to build a new monetary order [revealed in full here].
If this unfolds as my research suggests, the dollars in your wallet will look exactly the same, and the balance in your bank account won’t move up or down overnight.
But this reset could trigger a widespread repricing of goods, services and assets across the United States.
So if you have savings, if you’ve been building up your retirement, or if you own a stock portfolio, I believe you need to understand what’s happening to America’s money soon.
Because on December 14, when Trump hosts world leaders at his Doral resort in Miami, I think he could unveil his new dollar to the world in all but name.
In my view, there’s an enormous opportunity here – because a specific band of assets connected to this reset have already begun to ignite, and I’d like to show you which ones could be next.
That’s why I’ve recorded this briefing to get you up to speed. Inside, I reveal the investments I believe you should consider today to get on the right side of Trump’s dollar reset – and the types of investments to avoid as this situation unfolds.
Good investing,
Porter Stansberry
Birkenstock Reports Full-Year Numbers December 10. Here Is What to Watch.
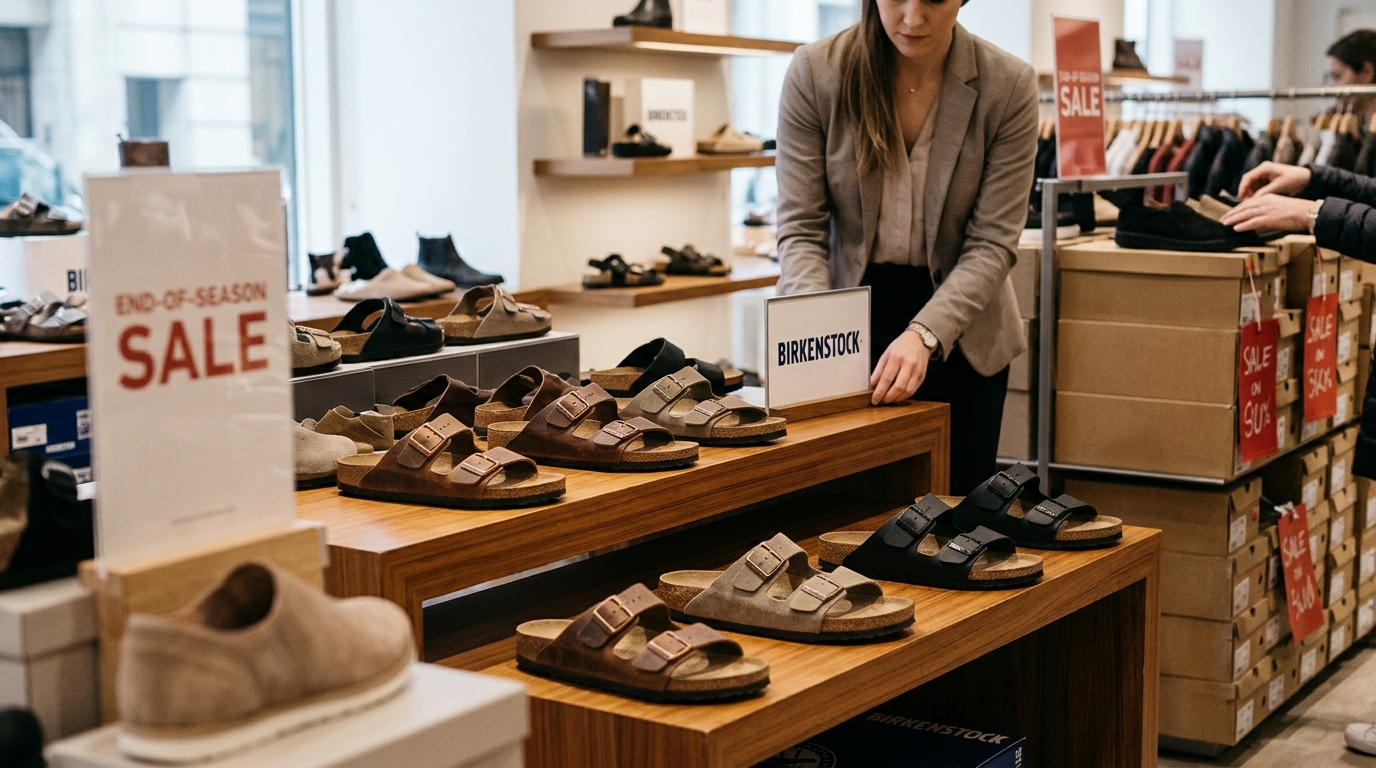
Most footwear brands enter the holiday stretch with one hand already on the discount lever. Birkenstock is not most footwear brands. While the broader retail industry is running promotional activity at elevated levels this season, with major retailers like Target rolling out early holiday deals to hold traffic, BIRK has said full-price sell-through remains strong at over 90%. That gap is the trade.
Birkenstock will release fourth-quarter and full fiscal year 2026 results on December 10, before the US market opens. That report will close the books on a year where the company spent three quarters proving its model holds even when macroeconomic conditions argue against it.
The Q3 numbers were the clearest signal yet. Revenue reached EUR 720 million in Q3 fiscal 2026, up 13% reported and 15% in constant currency, with adjusted EBITDA of EUR 242 million and a margin of 33.7%. More importantly for traders sizing this into the December report: direct-to-consumer growth accelerated to 16% in constant currency, outpacing B2B for the first time in two years. That channel shift matters because DTC expansion captures premium margins and delivers tighter inventory control.
The gross margin story is what separates BIRK from almost every peer in the sector. In fiscal years 2022 through 2025, Birkenstock’s gross margin stayed roughly in a 59–62% range, while many volume footwear brands run below that, a gap that is one of the clearest signals of pricing power. When the CFO was pressed on the Q3 call about whether pricing is passing through inflation, he clarified that all pricing decisions are made to protect gross margin, and said that year-to-date pricing over inflation benefited gross margin by 30 basis points.
The backdrop for December 10 makes the report more consequential than usual. Promotional activity has stayed elevated in parts of retail as consumers remain squeezed by higher prices. Retailers also continue to face cost pressure from tariffs and higher fuel and shipping costs, limiting their ability to absorb aggressive discounting. That is exactly the environment where brands without pricing discipline bleed margin and those with it pull away.
FY26 revenue growth guidance was raised to 15% in constant currency, resulting in reported revenue at the high end of EUR 2,300–2,350 million. The question the December report has to answer is whether APAC momentum continued through September. APAC has been growing faster than the other segments, and any acceleration there would expand the multiple case considerably.
The risk is straightforward: currency. Birkenstock has previously said currency translation can be a roughly 300–350 basis-point headwind to reported revenue growth, and FX headwinds have been a persistent drag on headline numbers all year. Traders watching the December 10 open should weight constant-currency figures, not reported ones, when judging the result against expectations.
The December 10 report is essentially a live stress test of whether premium pricing survives a holiday season built on markdowns. So far, the data says it does.