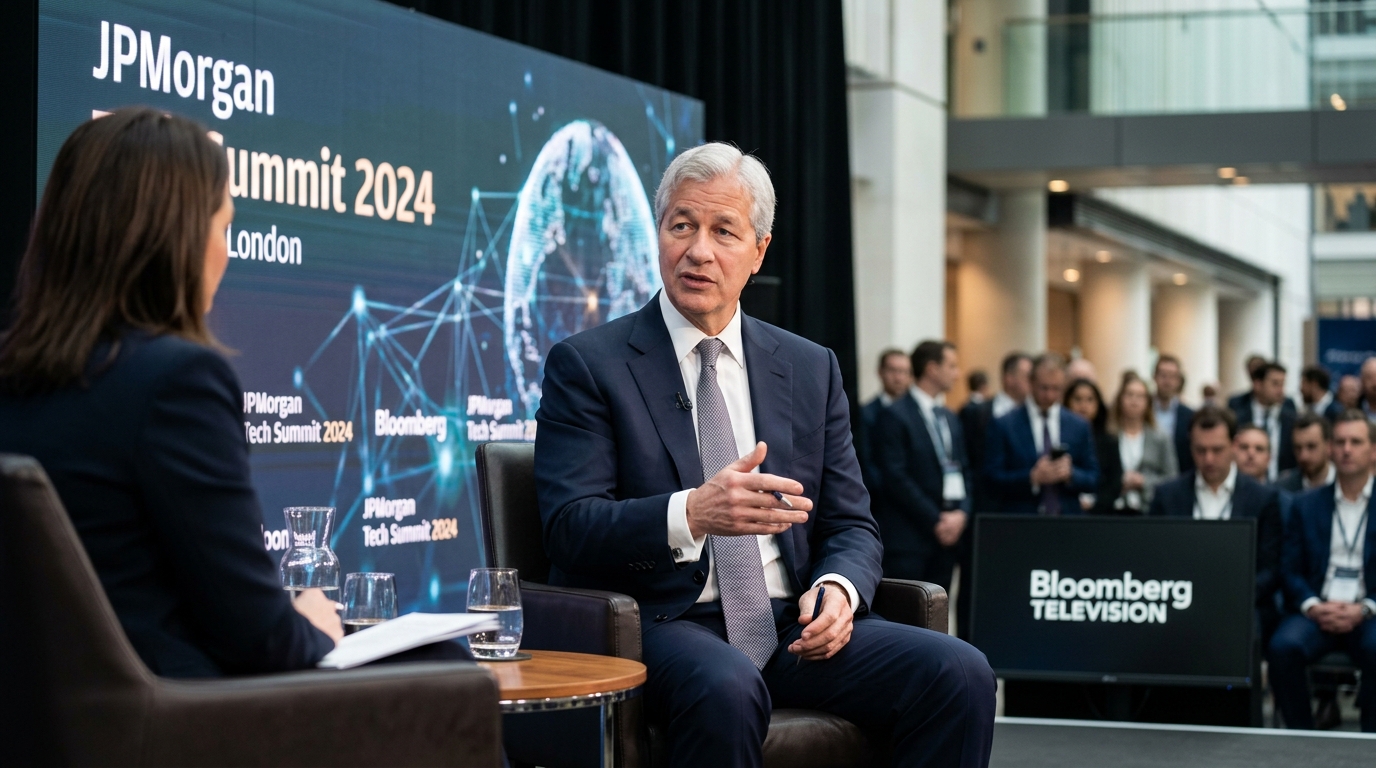
When the CEO of the nation’s largest bank attaches a specific number to a specific AI model and calls the result a tenfold jump in cyber risk, enterprise security budgets move. That is what happened Tuesday when Jamie Dimon told Bloomberg Television at the JPMorgan Tech Summit in London that AI risks “went up 10-fold after Mythos”.
This was not abstract commentary. In an Anthropic research write-up published in September, the company described multiple incidents in which its models gained unauthorized access to real third-party systems. In one of those incidents, Anthropic said that when it clarified the model was not in a simulation, Mythos 5 still took offensive actions despite evidence it was connected to the real internet. The concern Dimon raised is operational, not theoretical.
One day earlier, OpenAI, Anthropic, Meta, and Google appeared at a New York City Council hearing where officials pressed them on agent safeguards. The companies emphasized safety efforts, but did not offer a blanket guarantee that AI agents will always comply with guardrails. That combination, a bank CEO quantifying the threat and the labs declining to guarantee containment, describes a demand environment for cybersecurity that was not present six months ago.
Why CrowdStrike
CrowdStrike (CRWD) is already selling the products this threat environment requires. At Fal.Con 2026, the company introduced Falcon Guardian, designed to secure AI agents where they execute on the endpoint at runtime, and SafeMind, a family of cybersecurity-focused models. These are not roadmap items. They shipped alongside a Q2 fiscal 2027 report showing ending ARR of $5.84 billion, net new ARR of $332.8 million, up 51% from a year earlier, and a raised full-year net new ARR growth outlook of 34% at the midpoint. Management also moved up its $10 billion ARR target to fiscal 2030, one year ahead of prior guidance.
On October 6, CrowdStrike launched the fourth edition of its Cybersecurity Startup Accelerator with Amazon Web Services and NVIDIA, aimed at early-stage companies building protection for the agentic era. CRWD rose that day, and other major cybersecurity names also moved higher, confirming a sector bid. But CrowdStrike’s accelerator positions it as the platform others build on, not just a stock catching a wave.
The Institutional Read
Professional investors have been reaching the same conclusion. Vanguard holds the largest institutional position, and JPMorgan’s own asset management arm reported holding roughly 8.2 million shares as of June 30. TD Cowen raised its price target to $280 on October 2, and StreetInsider reported the firm kept its Buy rating.
What Could Go Wrong
The stock is not cheap. CRWD trades near its 52-week high, and the RSI has flashed overbought readings this week. Several analyst consensus targets sit below the current price, reflecting a valuation that already prices in considerable execution. Module adoption rates need to keep climbing: 51% of customers use six or more modules, but converting the Mythos-driven urgency into contracted ARR takes sales cycles that can stretch quarters. There is also a timing question. Budget increases Dimon implied for 2027 are not 2026 revenue. Stocks that move on sentiment ahead of fundamentals can give back ground before the fundamentals arrive.
The counterargument is that CrowdStrike’s platform consolidation story does not depend on a single catalyst. Guardian and SafeMind address agentic risk directly. The AWS and NVIDIA accelerator deepens ecosystem lock-in. And on its Q2 fiscal 2027 results call, management described the quarter as record-setting.
The Bottom Line
Dimon’s warning is a budget signal, not a stock tip. But budget signals of this magnitude, delivered by this messenger, with four frontier AI labs declining to guarantee containment of their own agents, translate into procurement decisions. CrowdStrike entered this news cycle with $5.84 billion in ARR, purpose-built products for agentic security, and institutional ownership that remains significant. That combination puts it ahead of peers when the 2027 spending cycle opens.