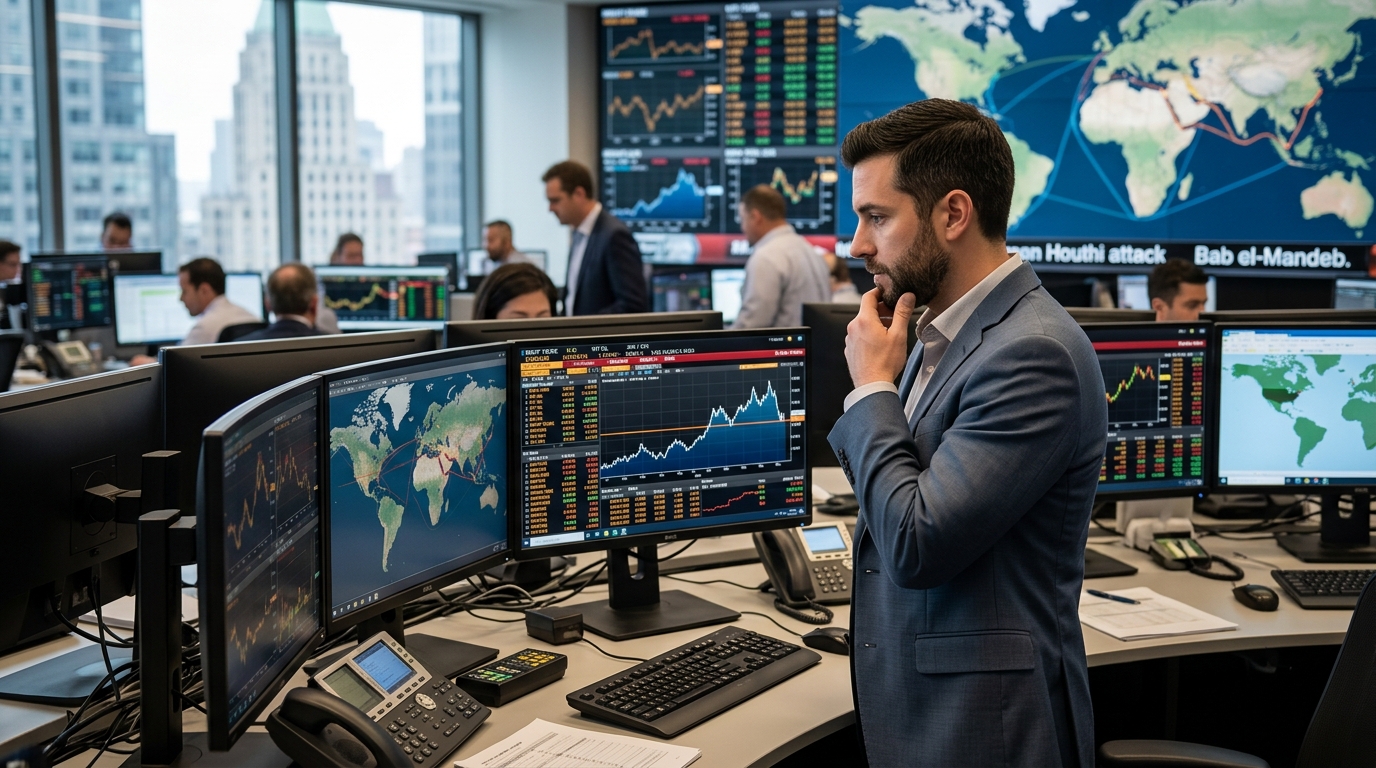
The Iran risk that oil traders spent weeks pricing in as a vague post-election threat now has a more specific window attached to it. Washington has warned Gulf allies to prepare for a possible new round of strikes on Iran after the US midterm elections, according to the Associated Press, citing two diplomats briefed on the matter. Some media reports have pointed to November 4 as an earliest plausible date, the day after the elections, but officials have not publicly confirmed that timing.
That caveat matters for risk management, but it does not soften what the market is already pricing. Brent’s December contract settled at $117.64 a barrel on Friday, capping a month that saw Brent advance 13.6% while WTI gained 15.2%. That is the fourth consecutive monthly gain, and the pace is accelerating.
The proximate trigger for Friday’s move was a fresh attack on shipping. UK Maritime Trade Operations reported a tanker in the Strait of Hormuz was attacked after assailants approached in a small craft and attached explosive devices to the hull. It was the latest entry in an October that turned brutal for maritime traffic. Reuters reported that October has been the worst month for attacks on commercial shipping in and around the Strait of Hormuz, with 28 incidents recorded by one tracker, rather than 35. Claims about October being “more than double” September, or March totaling 30 incidents, vary by dataset and could not be confirmed from primary reporting.
The Biggest Opportunity: Long Energy Into November 4
“Continued kinetic action around the Strait of Hormuz amidst doubts of a viable diplomatic pathway are keeping oil prices elevated in expectation of an escalation of the conflict in coming weeks,” said Saul Kavonic, head of energy research at MST Marquee. That framing is correct, but it undersells the near-term severity. A credible post-election escalation window is not a background risk. It is the primary variable.
The energy majors are reporting into this environment at full strength. Chevron reported adjusted earnings per share of $5.28 for Q3, alongside revenue of about $67.8 billion. Exxon said third-quarter earnings were $15.4 billion, or $3.72 per share. Chevron has noted that for every $1 change in Brent crude oil prices, its annual after-tax earnings and cash flow sensitivity is approximately $600 million. At $117 Brent, that sensitivity is working hard in CVX and XOM shareholders’ favor. Both remain the highest-conviction longs in the current environment: earnings momentum, commodity tailwind, and a geopolitical catalyst that has a calendar window on it.
The Brent tailwind does not stop at the majors. Hormuz disruptions have turned U.S. refiners into the world’s swing suppliers, pushing crack spreads into the high-$50s to mid-$60s per barrel.
The Other Side: Avoid Airlines
The same trade that works for energy breaks airlines. Jet fuel is one of airlines’ largest costs, often around a quarter of operating expenses, and with Brent above $115, those costs are compounding in real time. United Airlines reported Q3 revenue of $17.9 billion, up 17%, with adjusted EPS of $2.54 even with fuel expense up 62%. UAL’s operational strength is real, but it is running out of room to offset if Brent holds or moves higher through the post-election window.
The fuel shock is not uniform across carriers, and the divergence matters for positioning. United’s premium and international revenue streams have absorbed a larger share of the fuel cost increase than Delta managed, which changes the risk calculus for anyone shorting the sector indiscriminately.
Delta has previously estimated that a one-cent-per-gallon increase in the price of aircraft fuel would increase annual fuel expense by approximately $40 million, based on a company forecast for a prior year. DAL and UAL may retain some institutional support given their relative balance sheet strength, but the risk-reward for new long positions ahead of the post-election window is poor. The sector trades as a direct inverse of the Hormuz situation.
Trader’s Action Plan
XOM and CVX are the highest-conviction longs: fresh earnings beats, $600 million per dollar of Brent sensitivity at Chevron, and a geopolitical catalyst in the days immediately after the election. Watch Brent near $112 as the active trading level, with $120 back in focus if strikes are confirmed. The short side of airlines through the JETS ETF offers a clean hedge if that post-election escalation window holds. The warning signals preparation for a possible operation; it does not confirm that strikes have been ordered or will take place, so any diplomatic signal out of Qatar or a White House denial becomes the key risk to the energy long. Size positions accordingly.