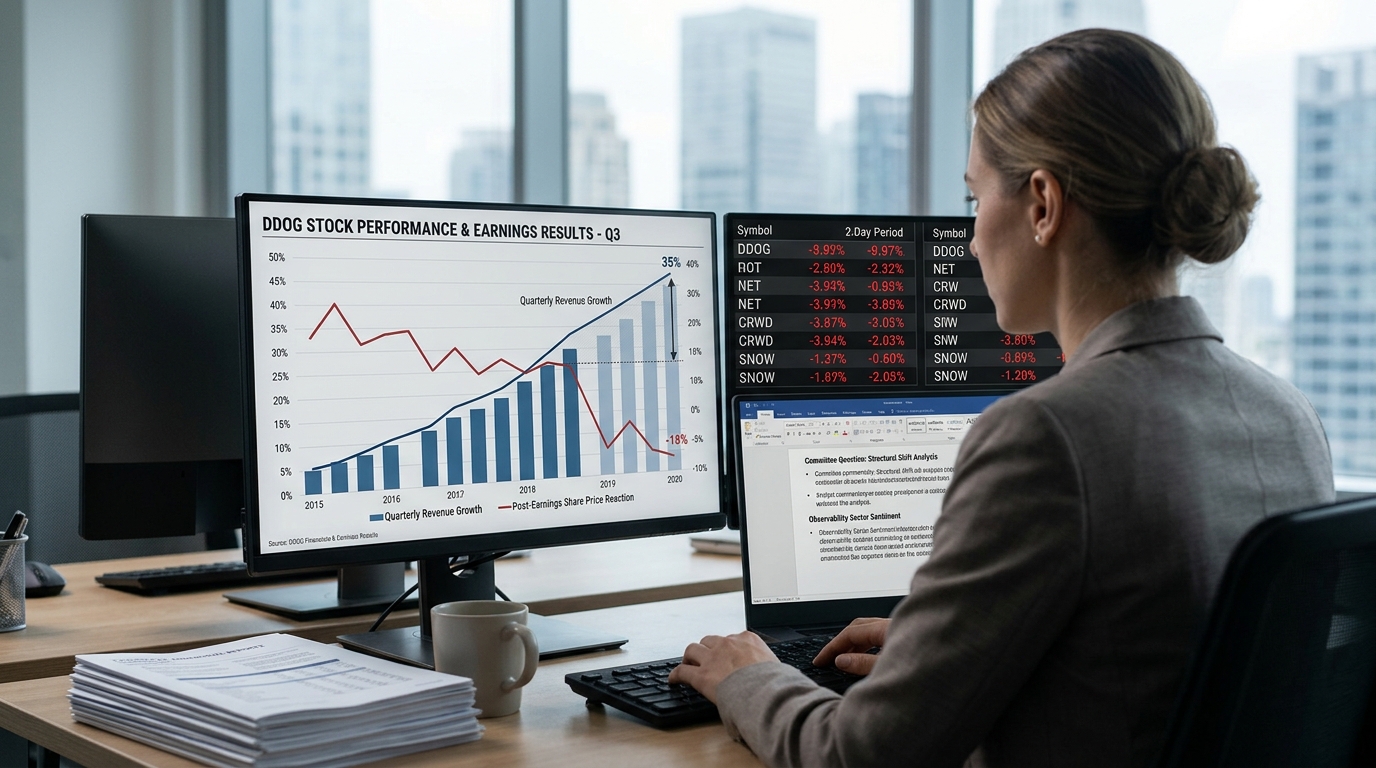
Datadog reported a nearly flawless quarter on November 4. Revenue grew 35% year over year to $1.20 billion, beating analyst estimates by about $50 million. Adjusted earnings per share of $0.81 exceeded consensus expectations. The company added roughly 800 net new customers above $100,000 in annual recurring revenue, reaching about 4,860, up from 4,060 a year ago. Free cash flow came in at $251 million. The stock fell 18%.
The proximate cause is well understood. Fourth-quarter guidance of $1.19 billion to $1.20 billion implies a growth deceleration to roughly 25% to 26%. Management said Q4 guidance assumes only the minimum commitment from its largest customer, even though that customer spent above minimum levels in Q3. Datadog did not say why its largest customer reduced its usage. Wall Street filled the silence with the worst interpretation available.
But the proximate cause is not the debate that belongs in an investment committee meeting today. The real question is structural: has the market permanently stopped paying a growth premium for enterprise software, and does two consecutive days of double-digit collapses in observability stocks confirm it?
The timing is not coincidental. On November 3, Dynatrace saw its shares plunge about 15% after it cut its full-year adjusted operating-margin outlook while raising its revenue forecast. Its Arize acquisition adds AI capabilities and an immediate hit to profitability. Two leaders in the same category, one day apart, both sold off hard despite top-line strength. The pattern demands an explanation beyond individual guidance lines.
The broader context matters here. The iShares Expanded Tech-Software Sector ETF posted a -24.3% 3-month return in early 2026, its worst such stretch on record. Goldman Sachs has pointed to software multiple compression tied to investor concerns that agentic AI could change traditional software business models. Datadog’s post-earnings collapse did not happen in a vacuum. It happened into a market that has spent most of 2026 asking whether cloud-infrastructure monitoring is a permanent growth category or a commodity waiting to be disrupted.
The bull case is not dead. Management said revenue growth across the customer base excluding AI customers was in the high-20s percent year over year. Management also said its Infrastructure Monitoring suite has surpassed $2 billion in ARR, growing at a mid-30s percent rate year over year. The underlying business, stripped of one concentrated customer, is holding up. That is not a deteriorating company.
The bear case, however, is now harder to dismiss. Investors have grown sensitive to any sign of deceleration in enterprise software spending, and guidance implying flat-to-lower sequential revenue outweighed the earnings beat and raised annual forecast. Datadog carried no margin for ambiguity. The market offered none.
The read-through spread immediately. A number of stocks fell in the morning session after Datadog projected fourth-quarter revenue that implied flat sequential growth, triggering concerns across infrastructure peers. Snowflake fell 2.9% and MongoDB fell 2.9% on a day when neither had reported earnings.
Stocks to Watch
Datadog (DDOG): The core business ex-AI customer is re-accelerating. If the concentrated customer risk resolves in Q1 2027, the multiple compression from 18% in one day creates a more interesting entry than investors had in September. The uncertainty is real, but so is the platform quality.
Dynatrace (DT): Dynatrace now expects a fiscal-year adjusted operating margin of 28% to 28.25%, versus 29.5% to 29.75% previously, with roughly 175 basis points of acquisition-related dilution. The Arize deal expands AI monitoring capability, but the market is paying for margin, not ambition, right now.
Snowflake (SNOW): Reports fiscal Q3 on December 2. Datadog’s consumption model functions as a barometer for enterprise cloud activity, and when a high-multiple cloud bellwether guides to flat sequential revenue, it raises concerns about a moderation in enterprise AI and cloud adoption. Any softness in Snowflake’s consumption metrics will face the same unforgiving reaction.
MongoDB (MDB): Caught in the same read-through selloff despite no incremental news. The question for MDB is whether developer-led consumption models are insulated from the enterprise caution signal Datadog just sent, or exposed to it in ways not yet priced.