Dear Reader,
With stocks hitting record after record…
It’s hard to deny we’re in a bull market.
America’s Economist, Dr. Mark Skousen, believes the greatest money rush of our lives has already begun.
But he’s also worried.
Skousen has called some of the biggest turns of the last 40 years.
He told his readers to sell everything a few weeks before Black Monday.
And in March 2009, the exact month stocks hit bottom, he told them to get back in. Sure enough… the market turned around and soared.
And today he’s out with a stunning new warning:
“A few of these companies could become the next Qualcomm. Hundreds more could become the next Pets.com.”
When we checked the record books, we were shocked.
In 1999 alone, Qualcomm soared up to 26-fold.
At the time, most people had barely heard of it.
And now, the same setup is here once again.
The trick is knowing which companies to buy… and when to walk away.
We recently sat down with Dr. Skousen to get the full story. And we recorded everything.
To watch it free of charge, click here now.
Good investing,
Rachel Gearhart
Publisher, The Oxford Club
Applied Materials Has Lost Half Its Peak Value. Thursday’s Report Has to Explain Why.
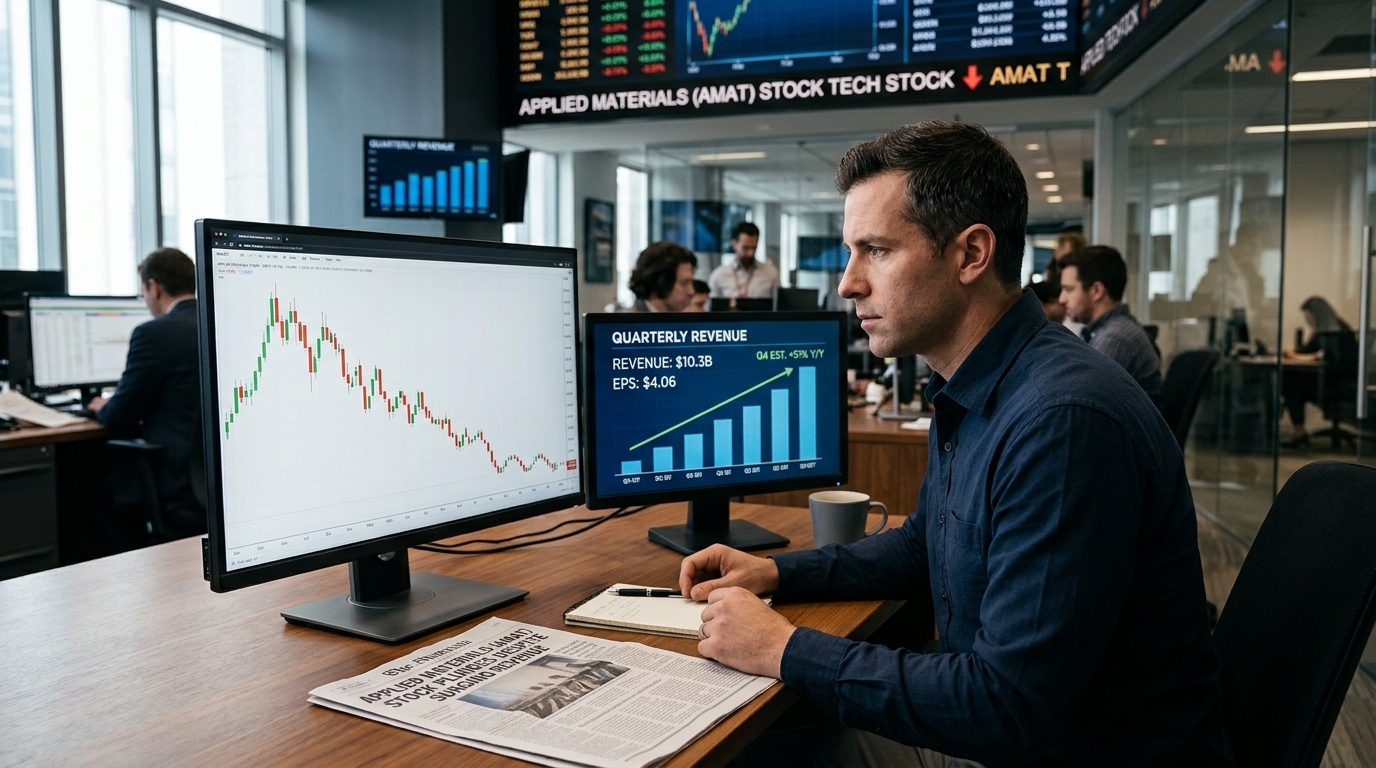
Applied Materials closes the books on its fiscal year Thursday, and the numbers Wall Street is expecting are genuinely extraordinary. Consensus revenue for Q4 FY2026 stands at roughly $10.3 billion, up about 51% from the same quarter a year ago. Adjusted EPS is forecast at $4.06, against $2.17 twelve months prior. The company’s own guidance, issued in August, called for $10.25 billion, plus or minus $500 million.
None of that has prevented the stock from becoming one of the most punishing stories in the semiconductor equipment sector this year.
AMAT’s 52-week high was $739.67, hit on June 30. It closed last Friday at $332.72. That is a drawdown of more than 55% from peak, against a business that management says is growing at record pace. Over the past month alone, the stock has lost about 14.7%. The RSI sat at 30.46 as of last Friday, right on the edge of oversold territory.
The selloff is not irrational in context. The period since late fiscal Q3 has been characterized by a broader semiconductor correction, with many chipmakers underperforming leading indexes. Morgan Stanley cut its price target to $538 from $563 on November 3, citing execution risks even as it maintained its hold. The concern is not that Applied Materials is building the wrong things. It is whether the spending cycle sustains long enough for the valuation to catch up.
That is the precise question Thursday’s report will force into the open. Management has raised its semiconductor equipment growth expectations multiple times in 2026, moving from more than 20% to more than 30% and then pushing further still. In Q3, Semiconductor Systems operating margin expanded to 38.0% from 33.2%, as DRAM, leading-edge logic, and advanced packaging orders accelerated. Those are the structural growth areas that matter most: HBM-linked DRAM and advanced packaging are AMAT share-gain areas.
The demand driving those AMAT order lines does not originate inside the equipment sector. HBM and advanced DRAM producers face a structural shortage that is pulling equipment spending higher across the memory stack.
What traders need from Thursday is not the Q4 beat. The beat is largely priced into analyst models. AMAT has beaten consensus EPS in each of the past four quarters, so another modest beat changes little. What moves the stock is the fiscal 2027 outlook. Analysts currently project FY2026 EPS of $12.79, rising to about $18.6 in fiscal 2027. If CEO Gary Dickerson reinforces that trajectory and signals continued customer order visibility, the stock finally has the catalyst to close some of that gap to the average analyst price target, which stands near $627.
The risk is a softer 2027 guide, or any language hinting that China revenue, which eased to 28% of sales in Q3 from 35% a year earlier, is compressing faster than previously modeled. The options market is pricing in an expected move of roughly 10% to 11% in either direction. At current levels, that is a swing of roughly $35 on the stock.
The fundamental case has not broken. The stock has. Thursday is where those two versions of Applied Materials either reconcile or diverge further.