Dear Reader,
Elon Musk can build rockets. Satellites. Factories the size of cities.
But he cannot build minerals he does not control.
I’m Dr. Mark Skousen. My career began inside CIA headquarters, spotting patterns before they became obvious. I warned about Black Monday weeks in advance and called the March 2009 market bottom.
And on January 1, 2027, a U.S. defense restriction expands across the full supply chain for certain covered magnets and strategic materials originating in China and other covered countries.
That is not a headline. It is a countdown.
|
Because every launch system, satellite network, military contract and AI buildout ultimately comes back to physical inputs. No minerals… no machines. No machines… no empire.
One small public company is pursuing a direct line to a vast new source of critical minerals – far from the traditional chokepoints that have trapped Western industry for decades.
The company is pursuing rights to recover mineral-rich nodules from the seafloor. Think of them as loose, golf-ball-sized deposits containing metals the 21st-century economy consumes by the ton.
This could give Musk something money alone cannot guarantee: a strategic supply line beyond China’s grip.
And if he chooses to buy rather than wait? The crowd will not receive a polite warning. The ticker could be repriced before most investors finish reading the press release.
My analysis has flagged this mineral play plus two other public companies positioned at the exact pressure points Musk still needs to control: compute and satellite communications.
|
A hard deadline is colliding with a strategic bottleneck. Waiting is now a decision of its own.
Yours for peace, prosperity, and liberty, AEIOU,
Dr. Mark Skousen
Macroeconomic Strategist, The Oxford Club
P.S. The January 1, 2027, rule is already on the books. Once the countdown hits zero, the market will not care that you meant to look at this later. This obscure mineral play could become essential to Musk’s empire. Learn more details before the deadline – click here now.
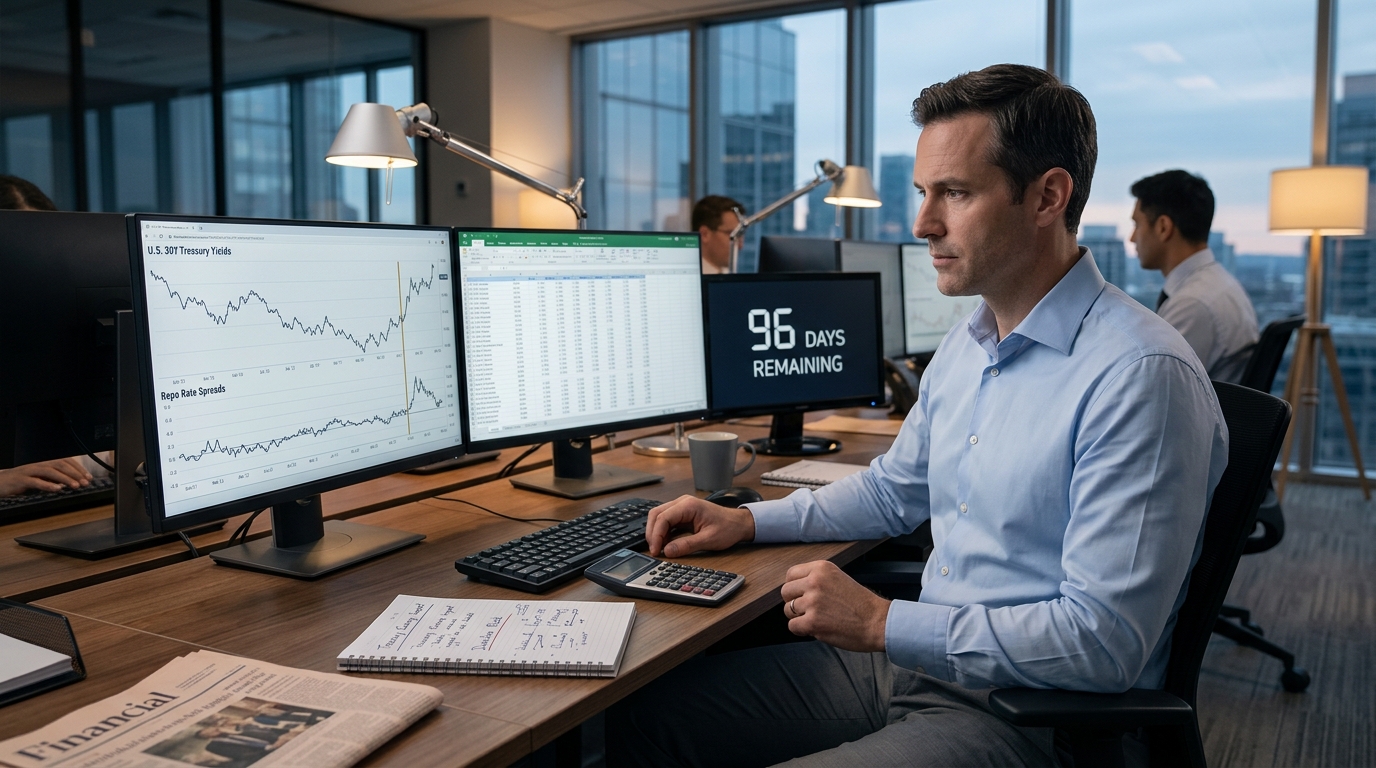
Treasury Clearing Starts in 96 Days. Duration Just Got Pricier.
The timing could hardly be worse. On September 22, the Joint Member Agencies convened the 12th annual U.S. Treasury Market Conference at the New York Fed, where the CFTC set out that agencies are working to deliver the SEC’s Treasury clearing mandate ahead of the December 31, 2026 deadline for cash Treasuries and the June 30, 2027 deadline for Treasury repo. Three days later, the 30-year Treasury yield rose as much as five basis points to 5.53%, having been below 5% as recently as early July.
That move did not arrive in isolation. The U.S. Treasury’s $70 billion 5-year note auction priced at 5.033% on September 23, posting the second-largest tail on record and sending 10-year yields toward 5.13%. The auction tailed by 3.1 basis points, with the bid-to-cover ratio dropping to 2.212, as foreign and institutional buyers pulled back sharply. Primary dealers absorbed 15.8% of the offering, meaning roughly $11 billion in supply landed on bank balance sheets the market didn’t want. Meanwhile, Japan’s 10-year JGB yield rose to its highest since September 1996, while gilts and German bunds also moved higher, with various European bonds hitting fresh multi-year highs.
This is the environment in which mandatory clearing arrives.
What Changes on December 31
Mandatory clearing begins for eligible U.S. Treasury cash transactions on December 31, 2026, primarily affecting trades between sell-side institutions. FICC, a subsidiary of DTCC, was historically the only covered clearing agency for Treasuries; CME Securities Clearing and ICE Clear Credit are now SEC-approved covered clearing agencies, with CME approved in December 2025 and ICE approved in early 2026. The mandate is structural, not optional. Historically, 70 to 80% of repo and cash trades were uncleared, creating vulnerabilities during market stress.
For traders carrying duration into year-end, the key issue is cost. A DTCC pulse survey of 340 industry experts released on September 22 found that margin costs are expected to rise 37% on average under the mandate. That number matters because the leveraged positions absorbing Treasury supply are margin-sensitive by design.
The Basis Trade Squeeze
The cash-futures basis trade, where hedge funds take offsetting positions in Treasury securities and futures, relies heavily on leverage through repo financing and futures margining. This leverage allows hedge funds to absorb more Treasury issuance at a time when primary dealers face balance sheet constraints. Hedge funds’ long Treasury exposures have expanded from roughly $600 billion in 2014 to $2.4 trillion at the end of 2025.
That base is already shrinking. Morgan Stanley strategists estimate that the notional value of leveraged investors’ Treasury basis positions has fallen to about $900 billion, down from approximately $1.26 trillion at the start of 2026, the smallest estimated size of the trade in more than two years. Mandatory clearing will tighten margin economics further, because bilateral repo, the low-cost funding that makes extreme leverage possible, gets pulled into the cleared system with its own deadline in June 2027.
The SEC and CFTC did provide a partial offset. Earlier this year, the CFTC and SEC approved exemptive orders allowing CME and FICC to expand their cross-margining arrangement beyond clearing members to customers for Treasury securities and futures positions. The potential savings are most significant for customers like hedge funds active in Treasury basis trading. Cross-margining helps, but it requires standing up new legal and operational documentation that firms describe as one of the largest implementation challenges, with bilateral agreements taking months to years to negotiate at considerable legal cost.
The Trading Implications
Reduce duration assumptions going into year-end. The transition from bilateral to centrally cleared trading raises the friction cost of leveraged long positions at the same moment that supply pressure and multi-decade yield highs are already weighing on prices. The basis trade is typically highly leveraged due to low or zero haircuts on repo borrowing and low margin requirements on futures. While it plays an important role in price discovery and liquidity, it also presents financial stability risks given its interconnected exposures across Treasury cash, futures, and repo markets.
The December 31 deadline does not mean the clearing impact arrives only on January 1. Counterparties are finalizing onboarding now. Firms not ready will pull back from bilateral Treasury transactions before the deadline, tightening liquidity into the year-end window. DTCC’s Laura Klimpel noted that while many firms are progressing toward readiness, more work remains, especially as it relates to the repo implementation. Watch for widening auction tails and elevated dealer absorption as the primary signals that leveraged demand is contracting. Both showed up this week. There is no reason to expect that to reverse while the yield curve sits at 22-year highs and the plumbing is being rewired underneath it.