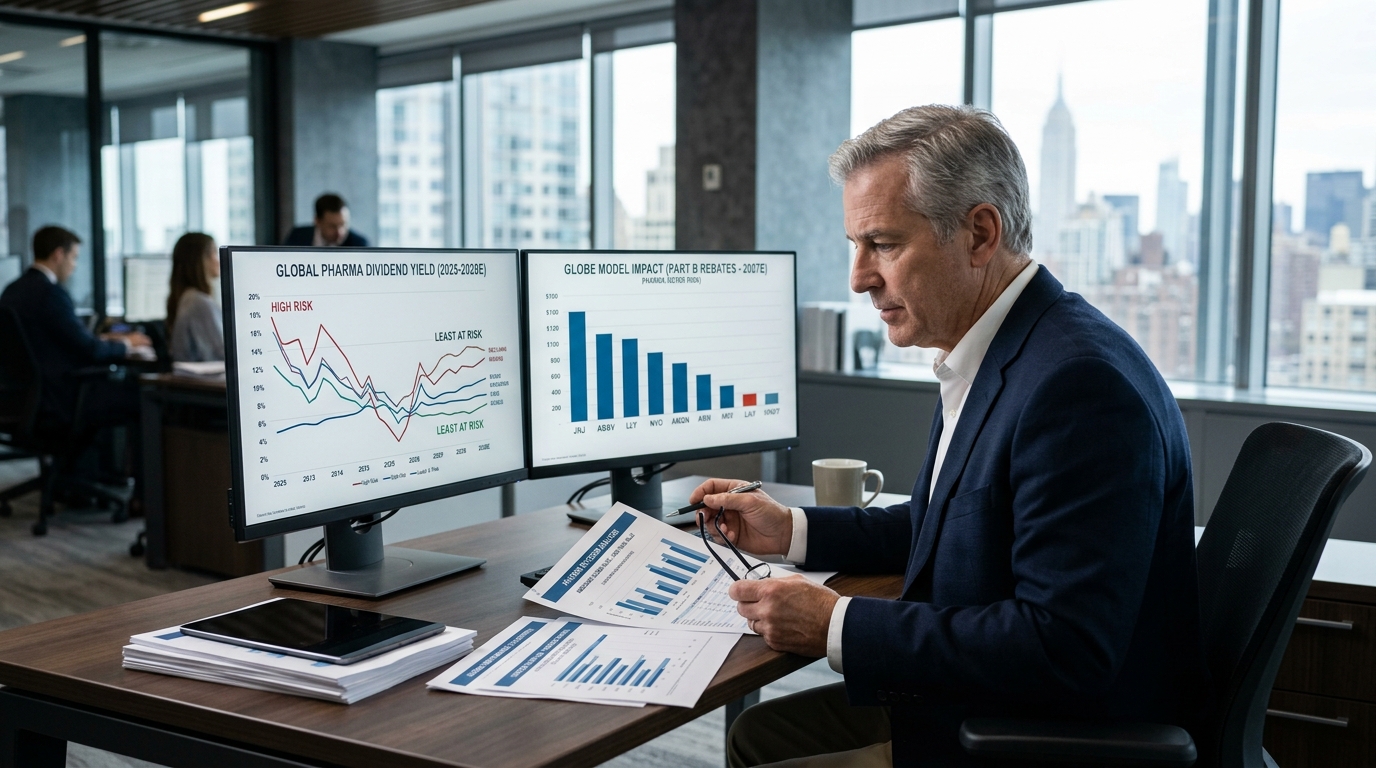
Two pricing shocks hit branded pharma within 48 hours last week. Section 232 tariffs on patented pharmaceutical imports took effect for most companies on September 29. Then, one day later, CMS finalized its Global Benchmark for Efficient Drug Pricing Model, known as the GLOBE Model, on September 30. For investors who own large-cap pharma for the dividend, the more durable question is not the tariff, it is what GLOBE does to the revenue lines that fund those payouts.
The mechanics matter here. GLOBE tests an alternative calculation for manufacturer rebates under the Medicare Part B Drug Inflation Rebate Program, using a benchmark derived from international drug pricing information. Those reference countries include Canada, France, Germany, Japan, and the United Kingdom. The model test period begins January 1, 2027 and runs through March 31, 2034, with the main rebate performance period running from April 1, 2027 through March 31, 2032.
Before you rethink the entire sector, read the fine print. The final rule is drastically smaller than what CMS originally proposed. Outside groups and policy analysts note CMS now estimates about $440 million in net Medicare Part B savings over the model’s seven-year payment period, down from roughly $11.9 billion in the proposed version. And the final model is expected to apply to only a handful of manufacturers, rather than the much broader sweep investors initially feared. GLOBE applies in randomly selected ZIP Code Tabulation Areas covering approximately 25% of Medicare Part B beneficiaries in Original Medicare who have Original Medicare as their primary payer.
Who Actually Gets Hit
GLOBE drugs are high-spend, single-source drugs and sole-source biologicals from oncology, rheumatology, immunology, ophthalmology, and endocrinology classes, with certain exceptions, where annual Original Medicare spending exceeds $100 million. That sounds broad. It is not, once the exclusions land.
GLOBE excludes biosimilars and their reference biologicals once a biosimilar enters the U.S. market. CMS also excluded orphan-only drugs, plasma-derived products, and certain cell and gene therapies in response to public comments. The biosimilar carve-out is the most consequential exclusion for dividend investors. Any Part B drug facing marketed biosimilar competition drops off the GLOBE list entirely.
That carve-out directly protects companies whose biggest Part B products have already attracted biosimilar entrants. Johnson & Johnson’s Stelara, for instance, has FDA-approved biosimilars, which can remove it from consideration once a biosimilar is marketed. Humira biosimilars have been on the U.S. market since 2023, shielding AbbVie’s legacy product from GLOBE rebate calculations, though Humira’s Part B volume is modest given its subcutaneous route. AbbVie’s current growth engines, Skyrizi and Rinvoq, are both posting strong growth in 2026, and there are no FDA-approved biosimilars for Skyrizi in the United States as of August 2026. That means any Skyrizi intravenous loading doses billed under Part B could technically qualify, but the primary administration route limits exposure significantly.
Where the Real Exposure Sits
Merck carries the most concentrated risk among dividend payers. Pembrolizumab (Keytruda) was the number-one Medicare Part B drug by total spending in 2023, at about $5.4 billion. Keytruda and its subcutaneous successor Keytruda Qlex together generated $8.4 billion in Q2 2026 sales alone. No biosimilar is on the market yet, which means Keytruda qualifies as a GLOBE candidate in its oncology class. That concentration cuts both ways: massive cash generation today, concentrated policy risk tomorrow. Merck’s dividend, while growing, is tethered to a single asset facing simultaneous IRA price-setting exposure later this decade and the GLOBE rebate framework starting in April 2027.
Regeneron’s EYLEA franchise sits squarely in GLOBE’s ophthalmology category. Regeneron settled patent litigation with Samsung Bioepis in February 2026, with that biosimilar blocked from launching in the United States until January 2027. Once that biosimilar enters the market, EYLEA would exit the GLOBE eligible pool, a protection that arrives just as the rebate performance period begins.
The Dividend Calculus
For income-focused portfolios, the practical conclusion is layered. AbbVie looks relatively insulated: its growth is concentrated in Skyrizi and Rinvoq, drugs with no current biosimilar competition but administered largely outside traditional Part B billing pathways, and AbbVie reported combined Skyrizi and Rinvoq sales of $25.9 billion in 2025, with company guidance pointing to more than $31 billion combined in 2026. The dividend trajectory looks intact. Eli Lilly’s largest revenue contributors are oral and subcutaneous agents in diabetes and obesity, outside Part B entirely.
Merck is the name to watch most carefully. GLOBE’s rebate mechanism applies to only about a quarter of Original Medicare Part B beneficiaries, and the total system-wide savings estimate is modest. But Keytruda’s sheer Part B footprint means that even a narrow model can register on Merck’s income statement. Merck’s dividend yield moves with the stock price, but the compounding of GLOBE, IRA negotiations, and eventual biosimilar pressure argues for treating it as a position to size carefully rather than add aggressively.
The Wealth Builder Takeaway
Policy risk in pharma rarely lands with a single knockout blow. GLOBE is real but smaller than feared, covering a limited set of drugs for a subset of Original Medicare Part B beneficiaries, with broad exclusions that knock many blockbuster biologics out once biosimilars are marketed. The dividend investor’s job here is straightforward: map each holding’s Part B revenue, check whether biosimilar competition clears the drug from GLOBE’s scope, and size positions accordingly. AbbVie and Lilly screen well on that test. Merck requires more vigilance. The lesson that travels beyond this week’s news: in regulated industries, understanding the exclusions in a new rule often matters more than the headline number.