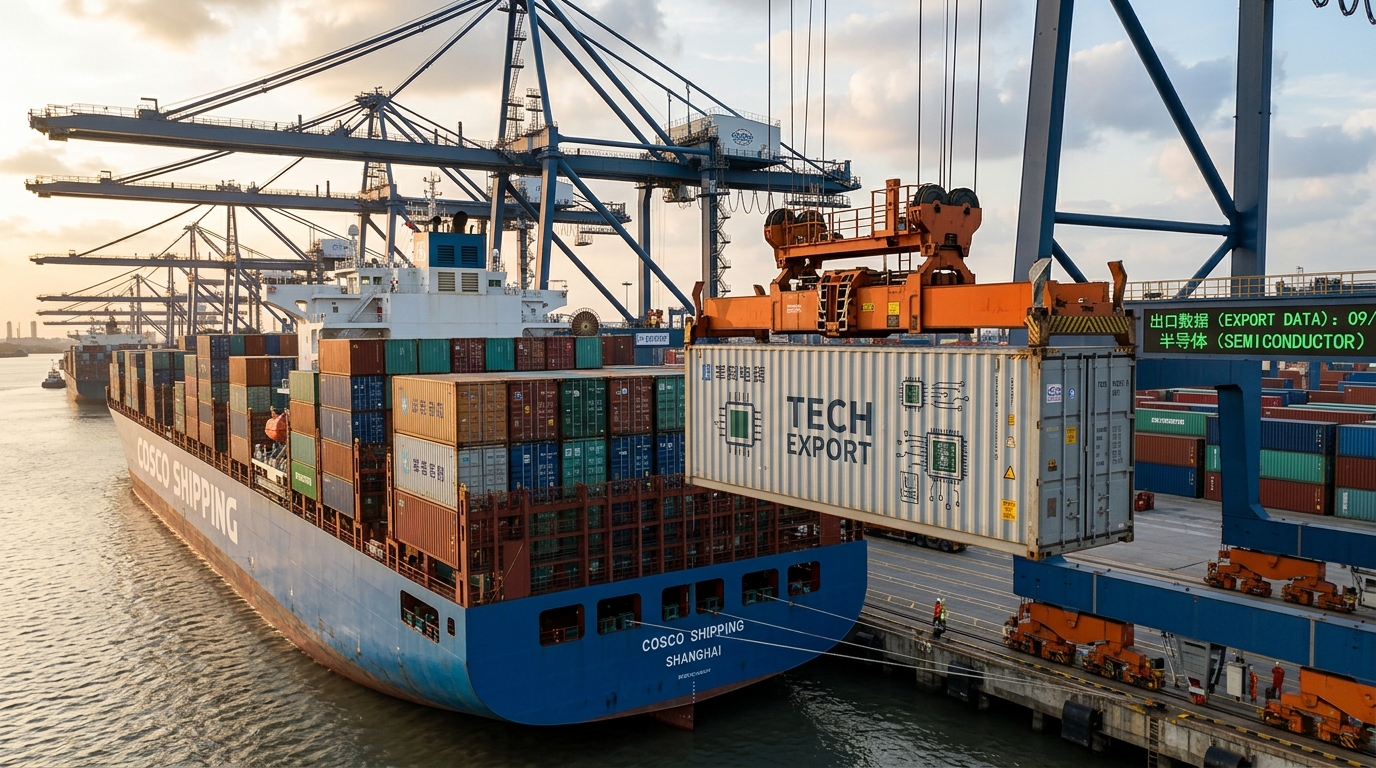
Wednesday overnight brings the most consequential China data point of the month: September exports and CPI, hitting screens before U.S. desks open. The number that sets the tone is not the headline surplus. It is whether chip-driven momentum held after two straight months of extraordinary gains.
Market Snapshot
China’s exports surged 25% year-on-year to $401.44 billion in August 2026, following July’s 23.9% increase, as the global AI infrastructure buildout continued to drive trade. The trade surplus widened to about $119 billion in August, lifting the January-August total to a record $806 billion. That is the baseline September must beat, match, or miss to move markets.
High-tech products accounted for more than half of export growth, with overseas sales of integrated circuits jumping nearly 130% and high-tech exports rising almost 57%. Claims that AI-linked hardware makes up 22.7% of China’s total exports vary by definition and could not be verified from primary releases, so treat that figure as an estimate rather than a hard statistic. A figure that large moves semiconductor stocks and the dollar simultaneously.
Stocks in Focus
Chip stocks broadly. Integrated circuit exports surged in August, but specific dollar totals cited across sources are not consistent and depend on product scope. Any deceleration in September would be read as a demand signal for the global AI hardware cycle. Strength would reinforce it.
Alibaba. A record surplus, concentrated in tech exports, keeps pressure on the EU trade relationship. Reports on August showed exports to the European Union rose 6.6%, but the claim that EU imports into China rose 0.7% could not be verified from a primary release and may reflect a narrower definition or separate cutoff. A widening surplus number Wednesday will sharpen Brussels’ attention on Chinese platform and logistics players, Alibaba among them.
COSCO, Maersk, Hapag-Lloyd. Volume matters more than value for carriers. Caixin reported that August’s headline growth was significantly propelled by higher prices for AI-related products, masking an underlying decline in the physical volume of goods shipped abroad. If September shows a similar pattern, freight rates do not follow the export value number higher.
Catalyst Calendar
- Wednesday, October 14: China CPI for September 2026 is due this day. Release time conventions vary by calendar, but it is widely tracked as an overnight event for U.S. markets. September trade data releases alongside it. The deflationary environment persists, with CPI previously tracked around 0.8%. A number below that reopens the stimulus debate.
- November 10: Market participants are watching November 10, 2026, when a one-year suspension of China’s expanded rare earth export controls is due to expire unless China extends the pause or amends the measures. The International Energy Agency has warned that full implementation could put $6.5 trillion of annual downstream production outside China at risk.
- January 10, 2027: The U.S. and China agreed to extend their existing trade truce by two months, setting a new expiration date of January 10, 2027. The brief two-month renewal fell short of expectations in parts of the market for a longer extension.
Risk Radar
The truce clock is the structural risk. Treasury Secretary Scott Bessent said the extension to Jan. 10 could buy time for further talks and that it is possible the current arrangement rolls forward again. Traders pricing in a smooth rollover may be underweighting January disruption risk.
Rare earths sit on a separate, closer fuse. If the suspension expires without renewal, the expanded set of controls, including the additional five rare earth elements, would be set to return to full coverage. That deadline arrives roughly four weeks before the tariff truce runs out.
The Cheat Sheet
- Top Theme: China’s chip export engine drove August’s record surplus; Wednesday tells traders whether September sustained the pace or stalled.
- Stock to Watch: Semiconductor names with China supply exposure. An integrated circuit export deceleration is the single data point most likely to move the AI hardware trade this week.
- Sector to Watch: Technology hardware. Specific claims that AI-related products contributed 8.6 percentage points to overall export growth in H1 2026 could not be verified from a primary release, so treat any such attribution as directional rather than precise.
- Biggest Risk: A miss on September exports, combined with CPI remaining at or below 0.8%, would simultaneously weaken the global AI demand story and raise the odds Beijing leans harder on further export acceleration to offset soft domestic consumption.
- One Thing to Remember: Wednesday’s number is not just a trade report. It is the first full-month read since the Xi-Trump summit, the last data point before November 10’s rare earth deadline, and the clearest signal available on whether the January 10 tariff truce will be treated as a bridge or a cliff.