Silver and gold are obliterating all previous profit records with next-level gains now on-deck for well-timed investors.
We’re talking early-stage, small-cap discovery stories that are only just beginning to unfold.
The early-stage opportunity is taking shape across a historic North American silver-gold district that helped build early fortunes but was never explored as a unified system.
For generations, the district produced high-grade metals at surface.
Yet, the deeper story was never told – not because the metals weren’t there but because the land package was highly fragmented and never explored as a single system.
That has now changed.
For the first time ever, this exceptionally well-run small-cap explorer has brought the entire district under one roof – enabling modern geology and drilling to finally test the system properly from surface to depth across kilometers of previously untouched mineralization.
And the timing couldn’t be better.
Phase-2 drilling is accelerating as you read this… setting up a near-term flow of potential needle-moving results as the discovery picture sharpens.
And that’s not all.
Add in a second nearby district-scale silver-gold asset… and the exploration runway expands even further for this emerging small-cap.
We’ve put together a FREE online report with all the details, including:
✓ A newly unified district-scale silver-gold system in North America
✓ What the first drill results are already confirming
✓ Which targets will see drilling next
✓ How a second district-scale asset expands the discovery upside
✓ Key 2026-27 catalysts as drilling intensifies
Inside, you’ll also find our exclusive, in-depth interview with the company’s president & CEO who brings a true firsthand look at where this discovery is headed next and why the timing is so critical.
Click here to access our FREE online report and see why this Sub-US$1 silver-gold stock is setting up to be one of the most compelling early-stage opportunities of 2026-27.
RTX’s $340B Backlog Has a Materials Problem Wall Street Is Ignoring
RTX just reported its strongest quarter in years. Adjusted EPS of $2.26 beat Wall Street’s $1.78 estimate by 27%, and the company raised full-year guidance for the third time in 2026, now targeting $7.65 to $7.75 per share. The backlog hit a record $340 billion, up 36% year over year. Defense bookings alone reached $59 billion in Q3, anchored by multi-year Tomahawk and AMRAAM contracts.
The financial story is clean. The materials story underneath it is not.
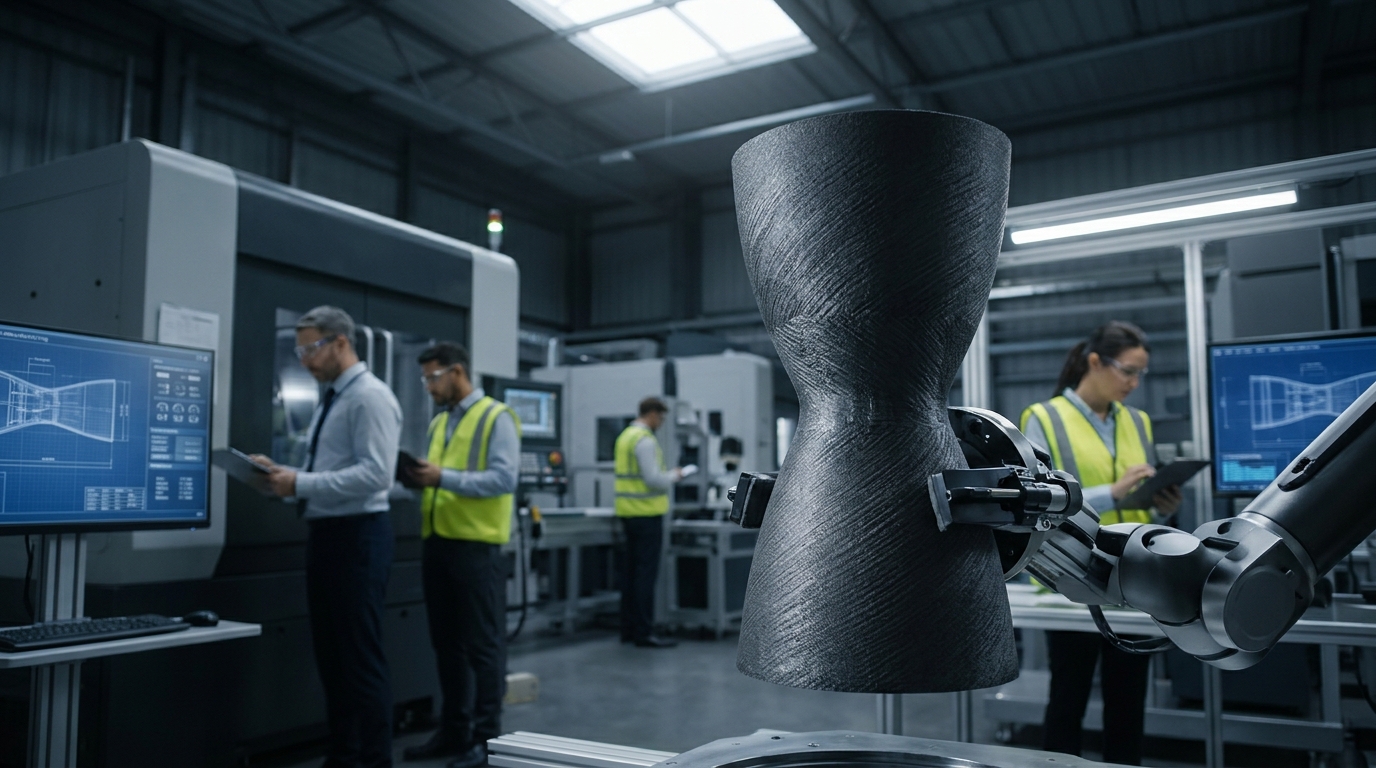
Every hypersonic weapon and flight system sitting inside that backlog depends on one class of material almost nobody outside the lab is discussing: ceramic matrix composites. CMCs are not interchangeable with legacy aerospace alloys. Traditional materials such as aluminum, stainless steel, and titanium cannot survive the temperatures generated at hypersonic velocities without thermal protection engineering. CMCs, alongside refractory metals and ultra-high-temperature ceramics, are built to handle that extreme heat.
The materials constraint is not unique to RTX. Howmet Aerospace has built a dominant position supplying precision-engineered, mission-critical engine components that face the same certification and production-ramp barriers.
Hypersonic systems operating beyond Mach 5 face punishing aerodynamic heating, abrupt thermal cycling, and structural stresses that push traditional alloys to their breaking points. CMCs, engineered for superior heat tolerance, strength-to-weight ratio, and chemical inertness, are proving indispensable. Specifically, CMCs can deliver meaningful weight savings versus metal designs while maintaining structural integrity at temperatures above roughly 1,300°C in certain aerospace applications.
RTX is directly embedded in this materials race. In June 2026, Pratt & Whitney appeared on the program for the 12th International Conference on High Temperature Ceramic Matrix Composites and 3rd Global Forum on Advanced Materials and Technologies for Sustainable Development, including a presentation on reinforced ultra-high-temperature ceramic matrix composites. RTX researchers are also active in this ecosystem, but the conference program does not support the claim that an RTX research center chaired sessions on coatings, integration, or machining.
Raytheon’s senior director of advanced hypersonic weapons, Wayne Tiffin, has stated that a 10-year development cycle for a new weapon must now get much shorter to keep pace with adversaries. That pressure lands directly on manufacturing throughput. Between 2026 and 2028, procurement will increasingly favor materials combining thermal protection, structural strength, oxidation resistance, and manufacturability. Competitive advantage will depend on shortening production cycles while maintaining repeatable extreme-temperature performance.
The market for hypersonic thermal protection materials was valued at roughly $625 million in 2025, and RTX sits inside the group of five companies that collectively hold about 40% of that market. But scale is the constraint. Suppliers that can pair high-temperature performance with reproducible fabrication and test evidence are better positioned than those offering only laboratory capability.
RTX also disclosed it has been adapting carbon-carbon composite brake technology to hypersonic applications, a low-profile line in a proxy filing that signals broader materials work than the company headlines publicly. Meanwhile, RTX has described expanding its internal test capabilities for weapon systems, including durability under extreme temperature and high-speed flight conditions.
The $340 billion backlog is the headline. The real question for traders with a multi-quarter horizon is whether RTX’s CMC production capacity can scale fast enough to convert classified hypersonic contracts into recognized revenue. That is the variable the earnings slides do not show you.